Five-Year Proforma
CNK Proforma · April 30, 2026. Revenue variability is intentional — structured around capital event cycles. 2028 and 2030 are peak capital-event years.
| Year | Gross Profit | Net Profit | Net Margin | Total Assets | Cash at Year-End |
|---|---|---|---|---|---|
| 2027 | $2,631,988 | $1,811,160 | 26% | $12,737,243 | $1,078,473 |
| 2028 | $11,274,120 | $10,540,408 | 43% | $24,570,904 | $4,560,853 |
| 2029 | $4,351,790 | $4,982,198 | 43% | $35,478,509 | $5,842,372 |
| 2030 | $14,127,531 | $15,773,915 | 49% | $49,582,385 | $4,148,031 |
| 2031 | $8,172,915 | $1,578,460 | 7%* | $50,148,357 | $1,414,846 |
| 5-Year Total | ~$40.4M | ~$34.6M | — | — | — |
*2031's 7% margin reflects final investment into the mixed-use building — generates $32,500/month passive income from 2032. Investment, not underperformance.
Three-Brand Platform
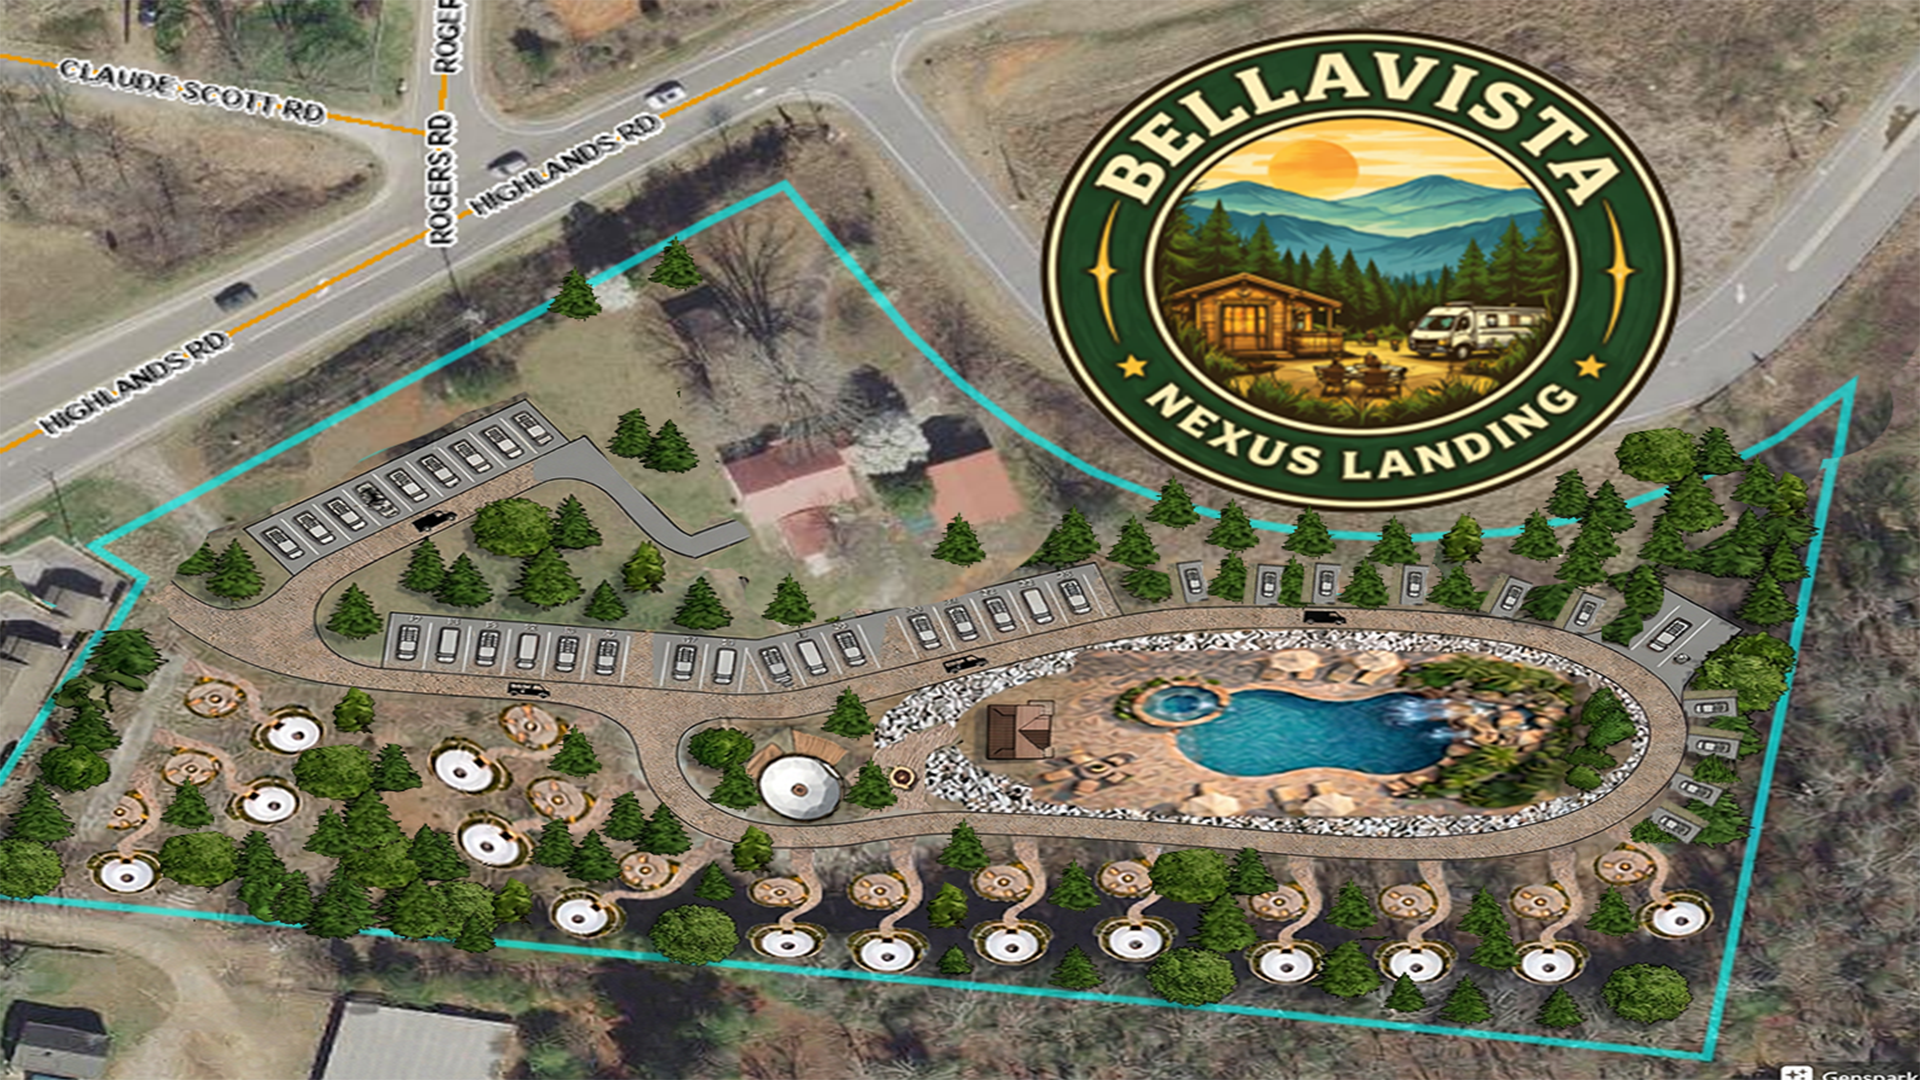
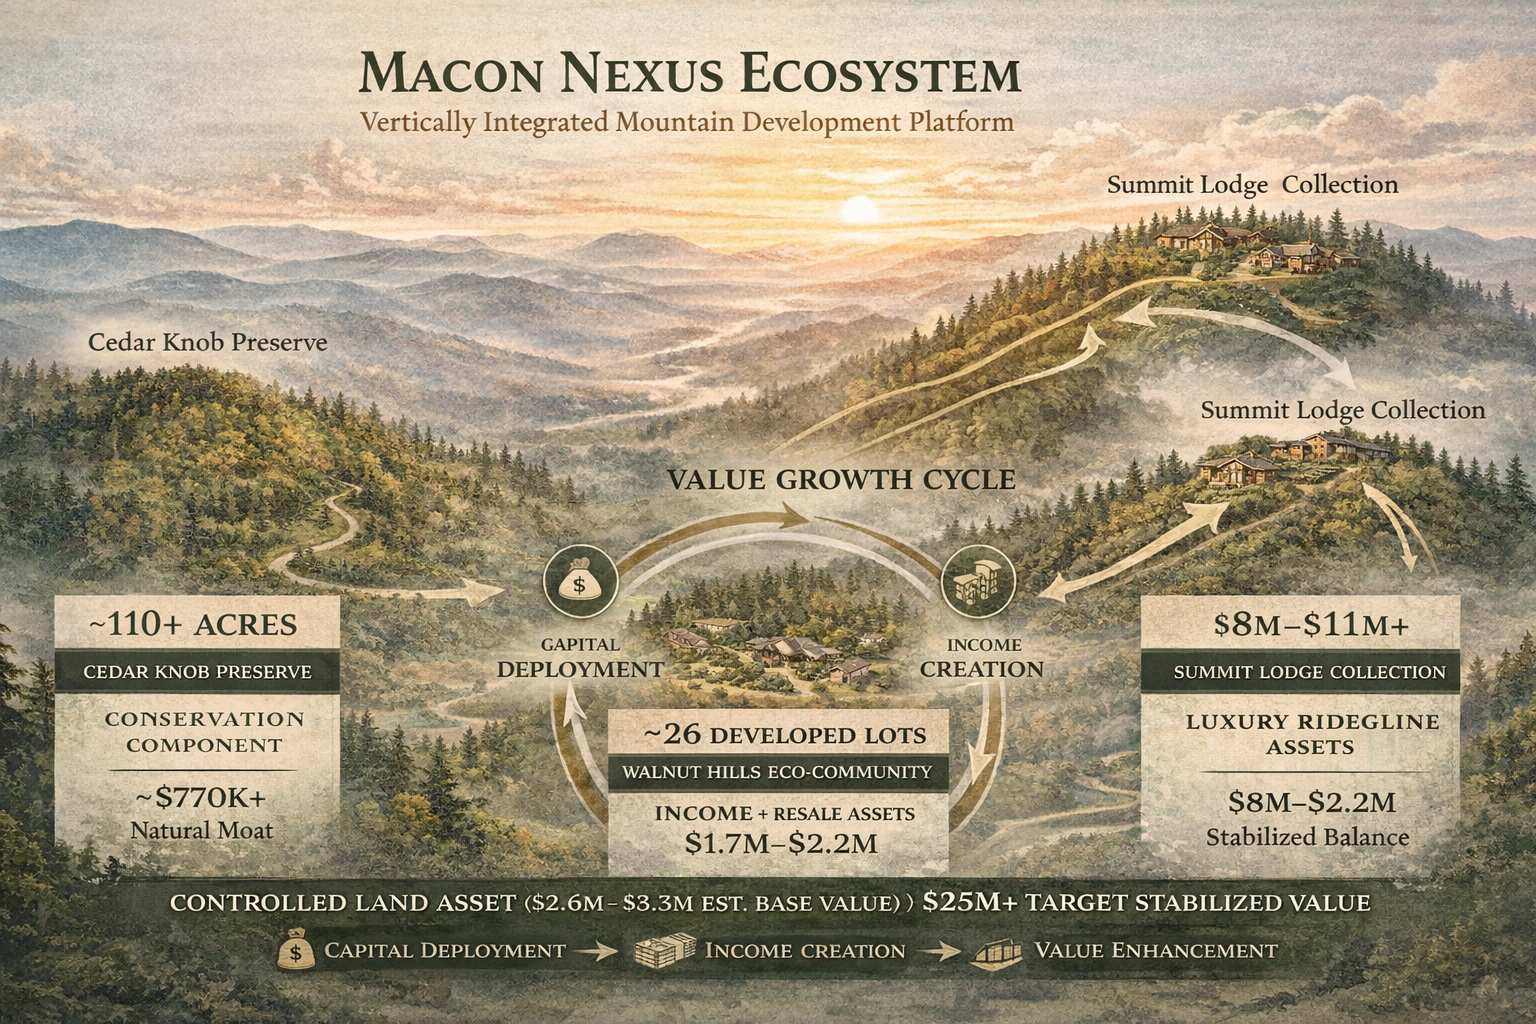
Three components operating simultaneously in a closed-loop system.

Revenue Stack
Five independent layers operating simultaneously. No single layer is required for the platform to remain viable.
$85K–$90K/month. Lease-backed assets covering baseline obligations, supporting DSCR and refinance confidence.
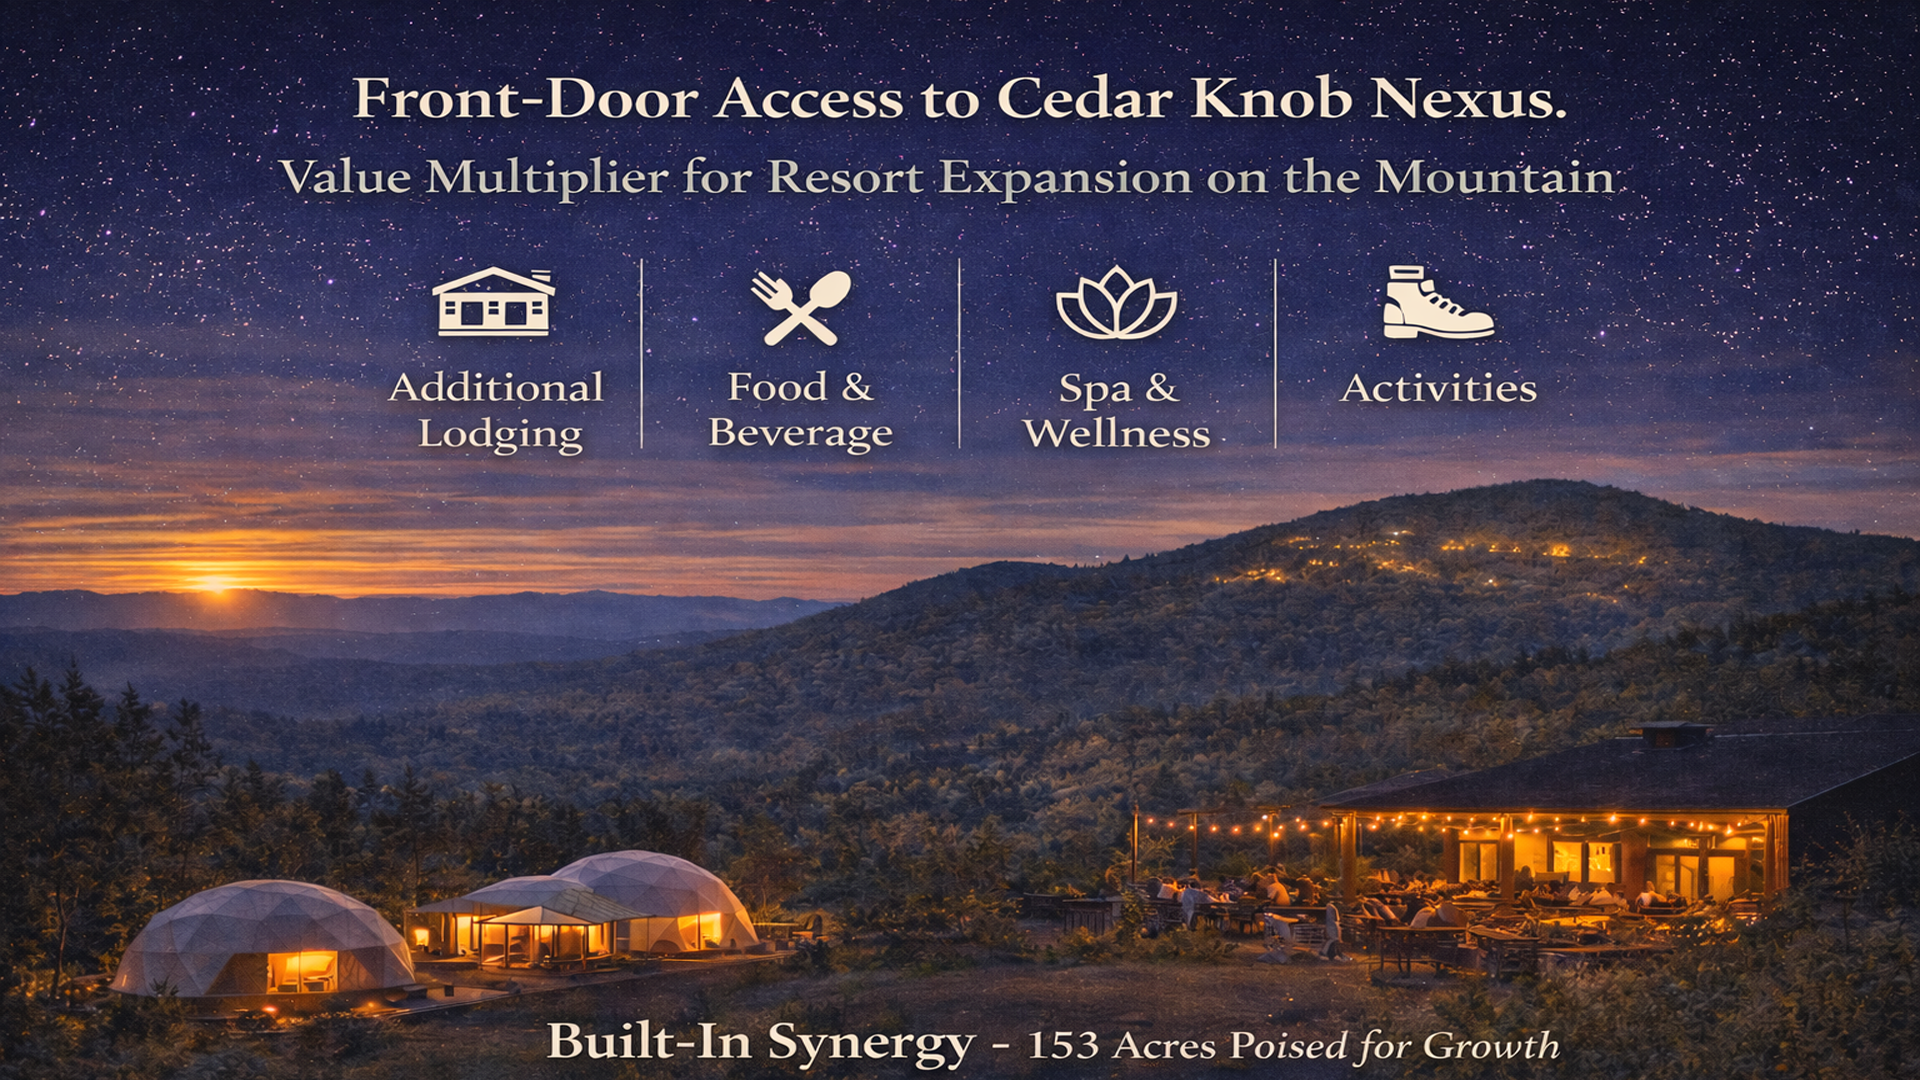
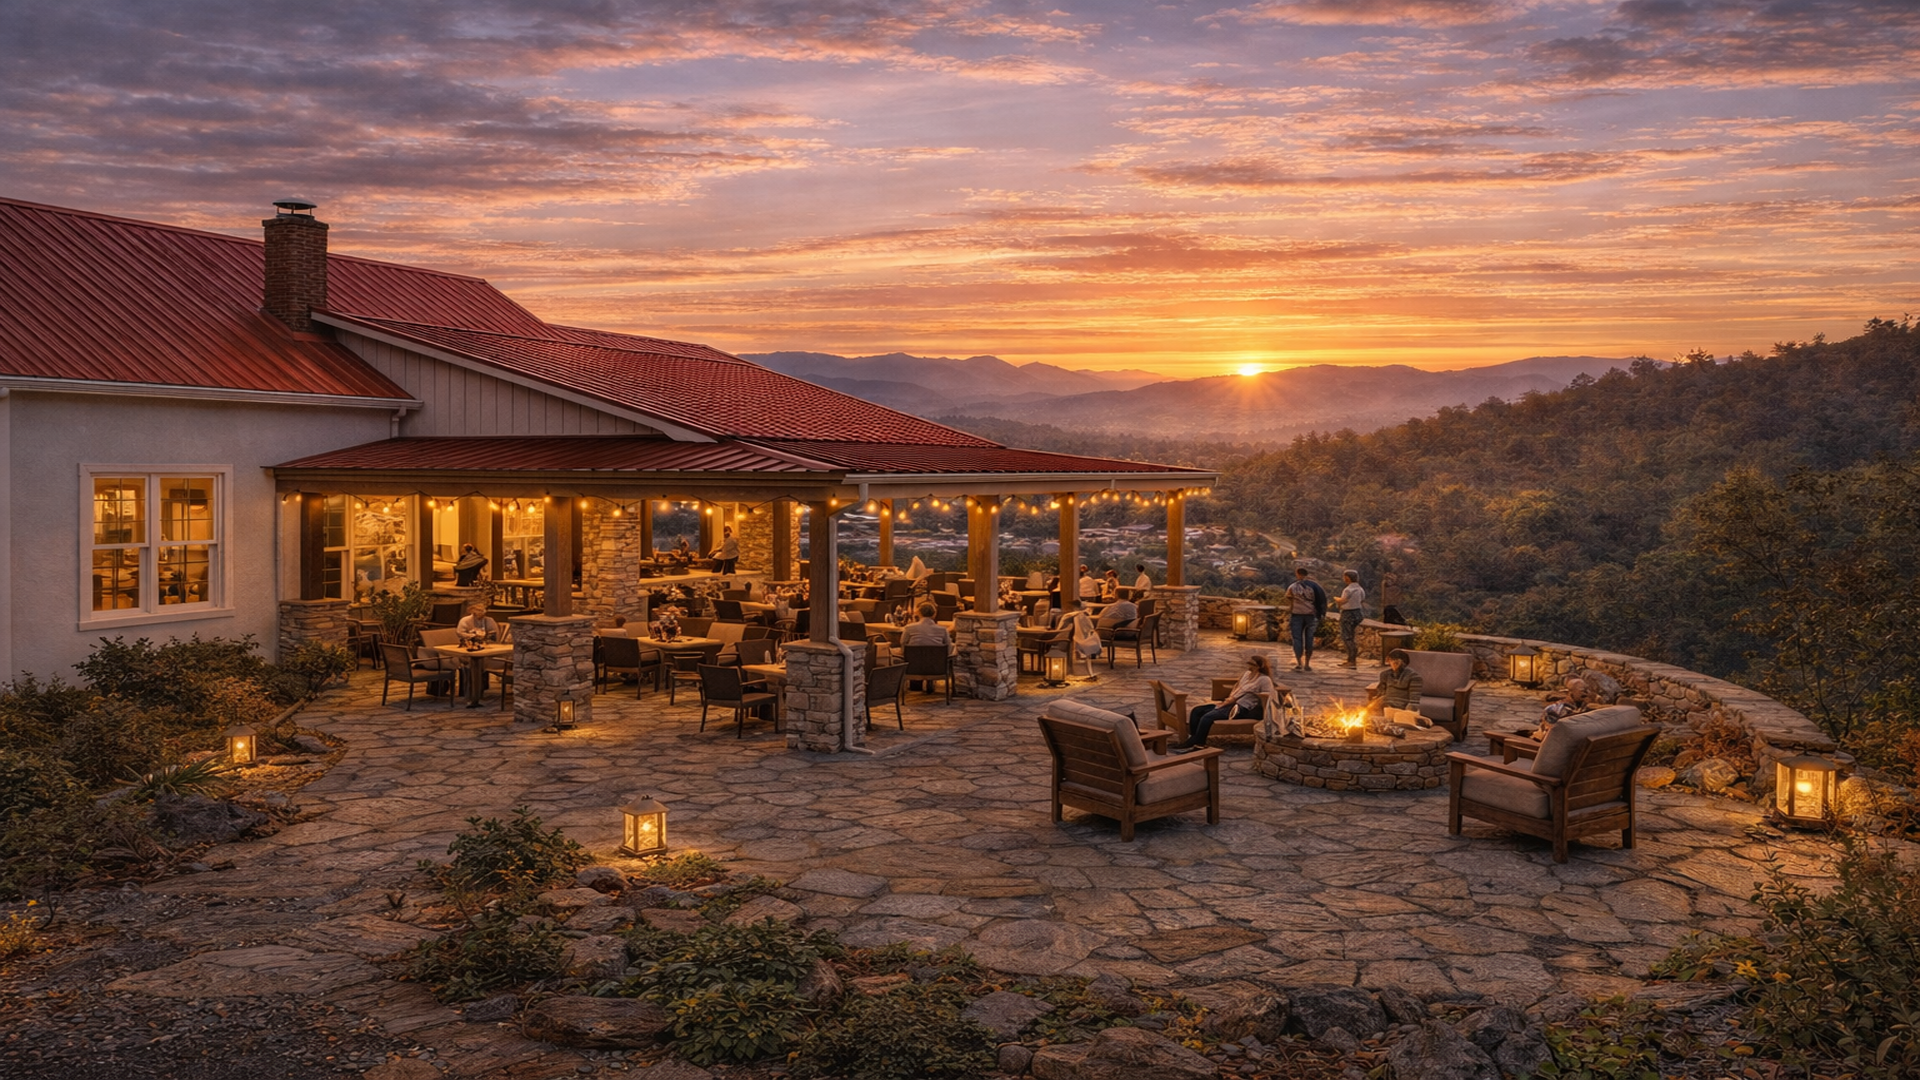
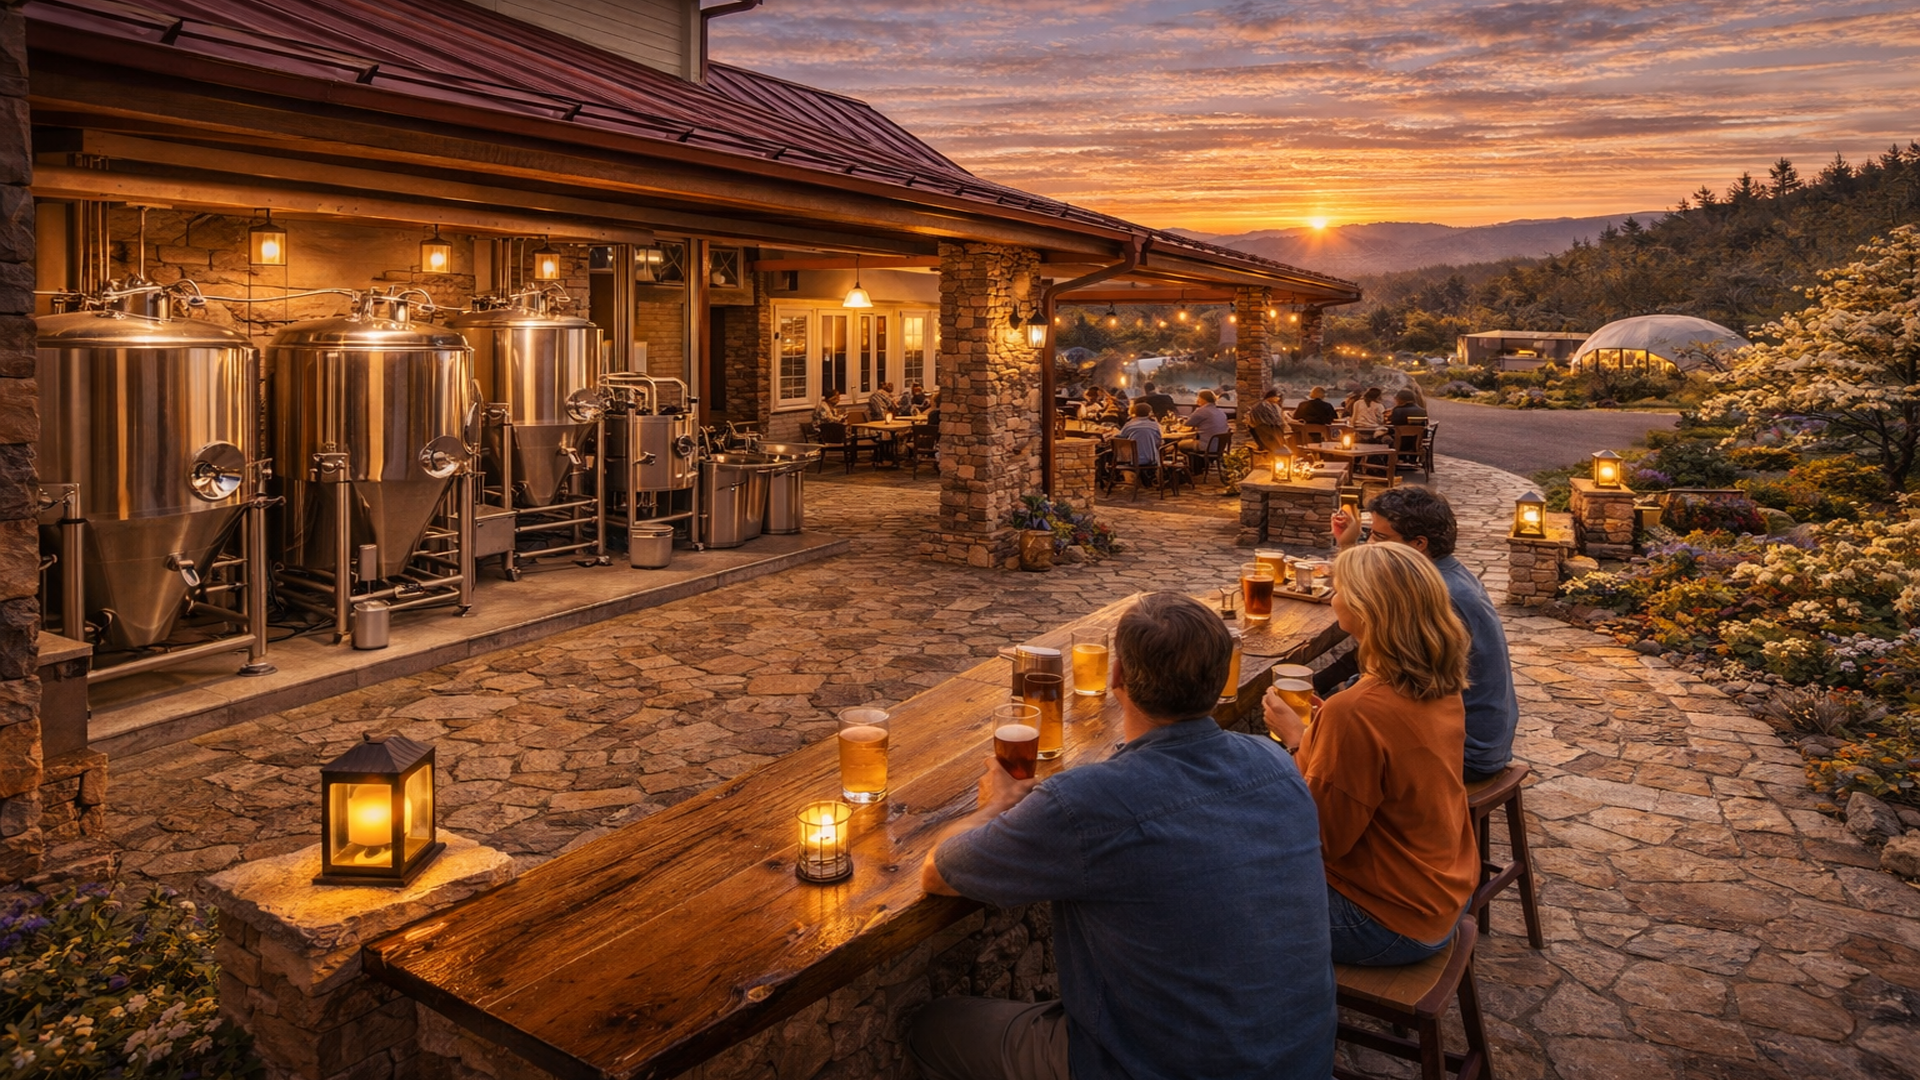
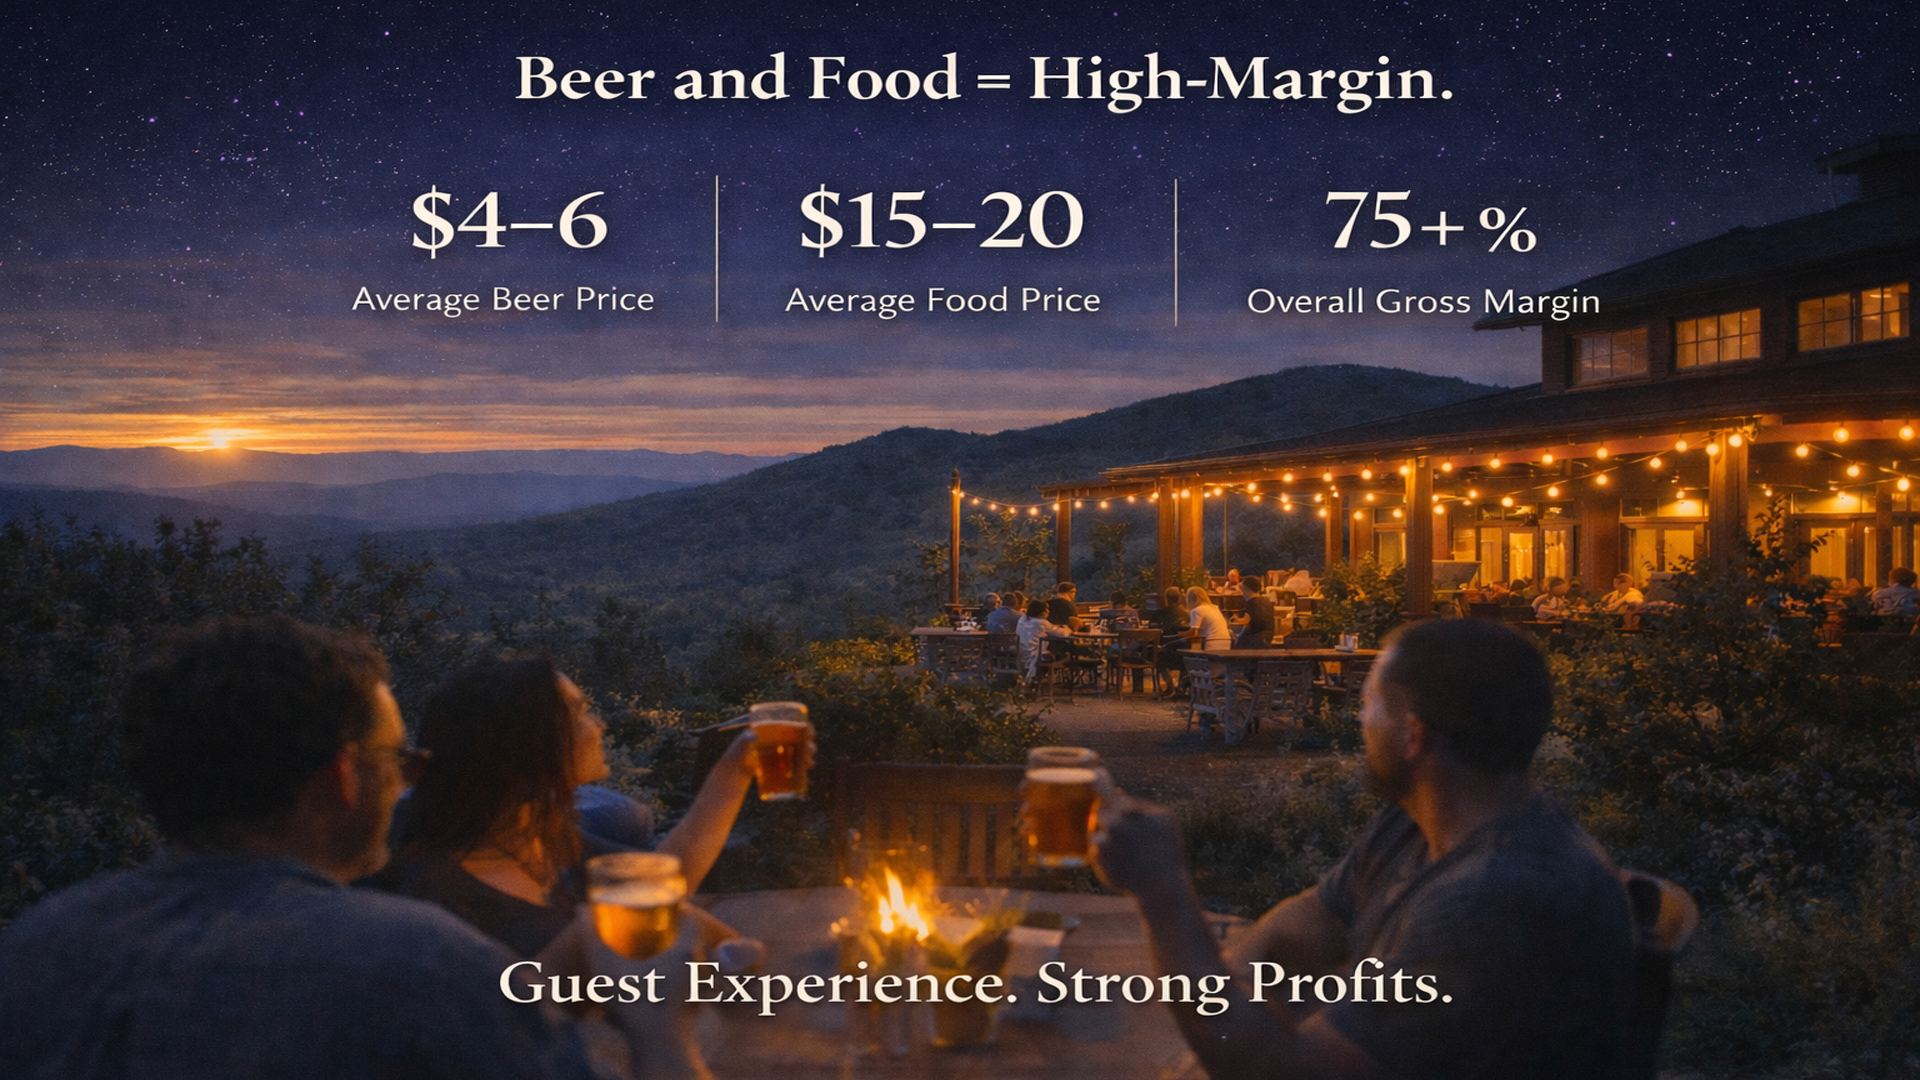
Restaurant $3.6M+/yr · Geodomes $1.3M+/yr · Craft ales, spa, deli, cottage rentals forming stabilized recurring cash flow.
Mountain Music Lodge ticketed events up to $1,390,000/yr. Workshops, retreats. Drives occupancy and per-guest spending.
WebWeave scales toward $1.7M+ annually. Home sales peak at $16M+/yr. Capital events fund each subsequent expansion phase.
Hard-Asset Foundation
Build-ready asset base — all barriers to entry already cleared.
- Infrastructure in place: Internal roads, underground power, shared well systems, build-ready inventory.
- 117-acre conservation easement: Rare high-elevation Montane Red Cedar-Hardwood Woodland, granitic domes, perennial streams. S2 designation. 130-acre natural backlot campus.
- Highlands-Cashiers-Franklin corridor: $1.2M median sale price Q4 2025. $36.7B NC visitor spending 2024.
2032 Stabilized Rent Roll
Passive income beginning 2032. Platform collects rent. Operators bear all operational risk.
| Metric | Value | Notes |
|---|---|---|
| Stabilized NOI | $789,468 | $1.435M revenue × 55% NOI margin |
| DSCR | 1.21 | $789K ÷ $650K estimated debt service |
| Valuation at 8% Cap | $9,868,350 | Income-based |
| Valuation at 7% Cap | $11,278,114 | Income-based |
| Valuation at 6% Cap | $13,157,800 | Income-based |
| Refinance Capacity | $6M–$7M+ | 60–70% of stabilized valuation |
Exit Pathways
Six parallel liquidity pathways operating simultaneously. No single exit carries the model.
Sacred Wellness Village units → secured notes → transferred to lender in satisfaction of debt. Eliminates traditional refinancing dependency.
2028–2030 window at projected $24M–$27M valuation. Clears early investor positions, recapitalizes at higher valuation.
~$14M institutional at stabilization. Based on $789,468 NOI, DSCR 1.21. Returns investor capital, optimizes capital stack.
Partial ownership resale reflects market-based valuation. Demonstrates realized value rather than projected appreciation.
Direct capital realization within an active, amenitized resort environment. Immediate liquidity and capital recycling.
Transition into income preservation. Debt-free. $861K/year passive rent roll. No single exit required.
$7M Documents
All materials specific to this raise.